Ordering Liabilities to Reclaim Your Agency
By Billy Coach Jr.4 min read
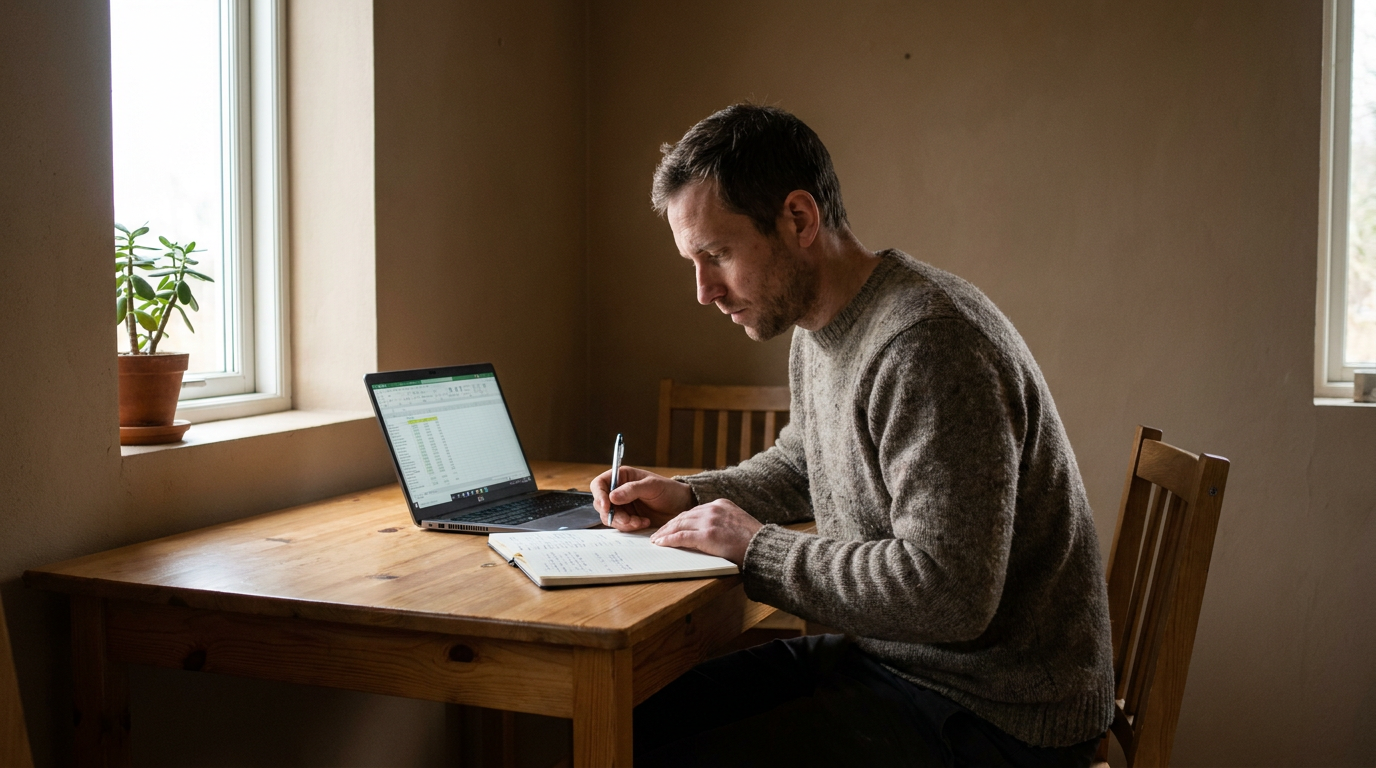
A disciplined strategy to eliminate interest drag, structure liabilities logically, and reclaim the mental bandwidth required for purposeful leadership.
High ambition and unmanaged consumer debt do not coexist comfortably. When an ambitious man owes money across credit cards, retail financing, or miscellaneous personal loans, the damage is not merely mathematical. The heavier toll is cognitive and spiritual.
Every outstanding balance represents an active claim on your future labor and a subtle siphon on your executive focus. You cannot make bold, long-term strategic decisions with uncompromised clarity when a fraction of your mental energy is perpetually allocated to managing monthly minimums and due dates.
The rich rule over the poor, and the borrower is servant to the lender. — Solomon
Taking control of your balance sheet is not about obsession with money. It is about removing friction so you can show up fully for your work, your family, and your calling. Ordering your liabilities is the first decisive step toward operational sovereignty.
The True Cost of Interest Drag
Interest on consumer liabilities is not simply an administrative line item. It is a recurring penalty paid for a lack of cash-flow margin. When you carry revolving balances, you pay a steep premium on past consumption using the energy of your future working hours.
In financial literature, this compounding drain is known as interest drag. A man carrying twelve thousand dollars across high-rate consumer accounts is not only losing capital each month; he is actively enriching an institutional balance sheet at the direct expense of his own family foundation.
This material is strictly educational. Individual situations differ, and complex tax or legal liability structures should always be reviewed with a qualified, credentialed professional. Regardless of personal specifics, the internal discipline required to inventory and eliminate liabilities remains universal.
Confronting the Full Inventory Without Evasion
Many men avoid looking directly at the total sum of what they owe. Ambiguity feels comfortable because it offers temporary emotional insulation. A man might know his rough monthly outflow while keeping the exact compounding percentages and total payoff dates conveniently blurred.
Discipline starts with unblinking visibility. A proper liability inventory requires listing every single obligation on a clean sheet of paper or an unadorned spreadsheet. For every account, document four distinct data points: the total principal balance, the annual percentage rate, the mandatory minimum payment, and the name of the lender.
When these numbers sit together in plain daylight, the emotional fog evaporates. You are no longer wrestling with an undefined cloud of stress. You are looking at a set of distinct, measurable targets that can be methodically dismantled one by one.
Choosing Your Attack Sequence
Once your liabilities are fully visible, you must select an execution strategy and commit to it without second-guessing. There are two primary disciplined frameworks for debt liquidation, each serving a distinct strategic purpose.
- The Avalanche Method (Mathematical Priority): Rank obligations strictly by annual interest rate from highest to lowest. Direct all surplus margin toward the highest-rate balance while maintaining minimum payments on all others. This approach mathematically minimizes the total interest extracted from your household over time.
- The Snowball Method (Psychological Velocity): Rank obligations by remaining balance from smallest to largest, irrespective of interest rates. Direct every surplus dollar toward the smallest balance to eliminate it completely. This creates immediate operational wins and reduces the total number of open accounts demanding administrative attention.
- The Strategic Hybrid: Eliminate one or two negligible nuisance balances immediately to clear operational clutter, then pivot fully to the highest-interest balance to stop the most aggressive cash bleed.
Both methods are effective when sustained. The single fatal error is a fragmented approach where surplus cash is scattered across several accounts simultaneously. Diffusing your effort dilutes impact and extends the duration of the campaign. Pick one target balance, concentrate your available resources, and eliminate it completely before shifting focus.
Manufacturing the Margin to Accelerate Payoff
Ordering your debts establishes the target, but payoff velocity depends entirely on cash margin. Minimum payment schedules are engineered by lending institutions to maximize their return by prolonging your repayment horizon over years or decades.
To break this cycle, you must intentionally manufacture a temporary operational surplus. This requires establishing a strict perimeter around your lifestyle: pausing non-essential capital outlays, auditing recurring service charges, and routing any irregular production income, project bonuses, or tax adjustments straight into principal reduction.
This posture is not an exercise in deprivation; it is a tactical mobilization. A man who tightens his spending to eliminate debt is not operating from scarcity. He is functioning like an operational commander clearing an encumbered supply line so he can maneuver freely in the future.
Execute Your Liability Audit Today
Authentic stewardship is not proven by the size of the resources you control, but by the order and integrity with which you govern them. When you systematically remove debt drag, you do far more than clean up your bank ledger. You lower your daily physiological stress, protect your household stability, and restore the mental stillness needed to lead well.
Take thirty uninterrupted minutes today to list every personal liability with its balance, interest rate, and minimum payment, choose between the avalanche or snowball sequence, and allocate an extra fixed dollar amount toward your primary target balance this month.
The Weekly Build
One weekly email featuring the latest two articles. Unsubscribe anytime with one click.